
FOUR QUESTIONS: Cleaner Steel Here in the US
April 8, 2022
How Clean is the Steel Industry in the United States?
The GEI report finds the U.S. produces the second cleanest and low-carbon steel in the world. The United States, which is the 4th largest steel producing country, making over 85 million metric tons of steel in 2021, trails only Italy (the second smallest steel producer included in the report making just 24 million metric tons). Among the six largest steel producing nations—China, India, Japan, the U.S., Russia and South Korea—which account for 75% of global steel production, the U.S. has the lowest CO2 intensity. The CO2 intensity of steel made in the U.S. is half of the amount of carbon per ton of steel made in China and India, the world’s two largest steel producers. Yet despite making some of the lowest carbon steel in the world, the U.S. also imports more than any other country. Most of that steel comes from places with significantly higher carbon intensities. Part of the problem is no mechanism exists to incentivize or reward U.S. manufacturers for producing some of the cleanest steel in the world.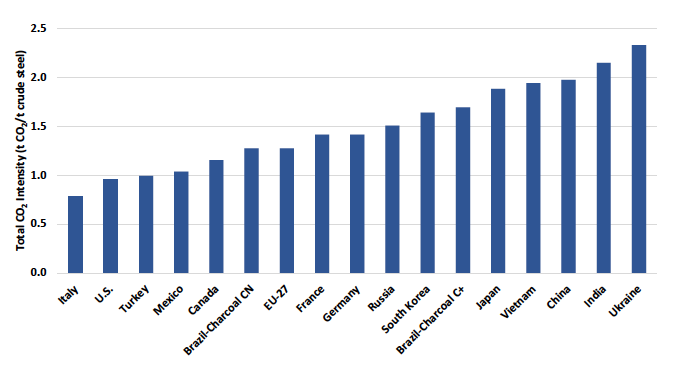
What can be done to create a market for lower carbon steel and other products?
BGA has been advocating for Buy Clean policies, which would prioritize purchasing construction materials—like steel, cement, and aluminum—from companies making these materials in efficient, lower polluting ways creating an incentive for companies to reduce their emissions and rewarding the firms that have already done so. Think about the construction of a bridge, where massive amounts of steel and concrete are used. Governments can either buy cheap, low-quality materials made overseas with high emissions, or they can purchase materials made by American workers with lower emitting processes (as we see with the GEI study) and stand with domestic manufacturers doing their part to fight climate change. The choice is pretty simple in our view. Buying cleaner means better quality, fewer emissions, and supporting jobs at businesses doing right by our environment. The policy would have several different components. It begins by collecting data from manufacturers on the estimated GHG emissions for a construction material through the use of environmental product declarations (EPDs). Think of it as the nutrition labels you would find on loaves of bread at a grocery store. Two loaves of bread may look identical and even taste the same, but by looking at the label you can identify the healthier loaf. The government can identify the materials with the lowest “embodied carbon”—the total of all of the carbon emissions created by a material’s production from when it started as a raw material in the ground to when it became a key component of a bridge, for example—and use the less polluting one. Thinking back to the bridge example: Imagine that two governments are investing in building bridges. Government A does not have a Buy Clean policy and uses taxpayer money to purchase cheaper, low-quality materials from overseas with a higher amount of embodied carbon, adding to the emissions driving climate change. Government B has a Buy Clean policy and uses tax dollars to buy high-quality products from U.S. manufacturers that have lower embodied carbon. The money they invested goes back to companies and workers here in America who are producing these products and materials. Paired with investments in industrial transformation, Buy Clean would create a new market that rewards companies for reducing emissions. That’s why Buy Clean is a win for the environment and for workers, and a win for you and your community. What investments are needed to drive industrial emissions reductions? BGA has been advocating for a series of strong investments in industrial transformation. This begins with important funding for the Department of Energy included in the historic Bipartisan Infrastructure Law. That law includes $550 million to provide technical assistance and grants for energy efficiency and emissions reduction at small and medium-sized businesses. There is also $500 million for project demonstrations of technologies to specifically reduce industrial emissions. There is also significant funding for programs and technologies that expand beyond the industrial and manufacturing scope, such as $3.47 billion for carbon capture, utilization, and storage that can be used to fund technologies to capture GHG emissions from steel facilities along with $8 billion to create regional hydrogen hubs that can be used to retrofit steel facilities to run on hydrogen. While this funding is an important first step in transforming American industry, BGA has also advocated for robust funding to help establish new domestic supply chains, spur development of new technologies, and modernize and cut emissions from industries like steel, cement, and aluminum. BGA has estimated that investing around $60 billion in manufacturing and industrial transformation would create 1.27 million jobs over 10 years and would also create or sustain hundreds of thousands of long-term jobs at thousands of factories established, expanded, or retooled with federal support and more throughout the economy. These investments would significantly reduce greenhouse gas emissions. The direct investment in industrial emissions reduction proposed in the Senate’s reconciliation package can achieve an emissions reduction of aproximitaly 100 million metric tons of greenhouse gas emissions. Why is it important to reduce industrial sector emissions? In the U.S., industry is responsible for 23% of direct GHG emissions, the third largest source behind just transportation (29%) and electricity production (25%). However, distributing electricity by end-use— reveals that the industrial sector is the second largest source of emissions in the United States, responsible for 30% of emissions overall. Globally the International Energy Agency (IEA) has calculated that industry is the largest emitting sector, with over 40% of global GHG emissions after allocating electricity and heat emissions to final sectors.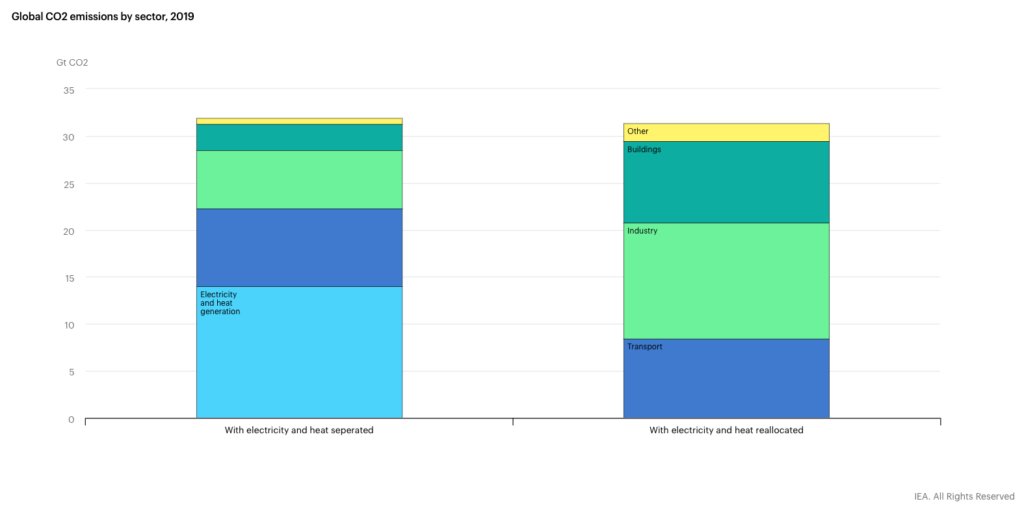
From International Energy Agency.